
Categories
BothellPublished July 20, 2026
Mortgage Rates in Bothell, WA: What Buyers and Sellers Expect This Year
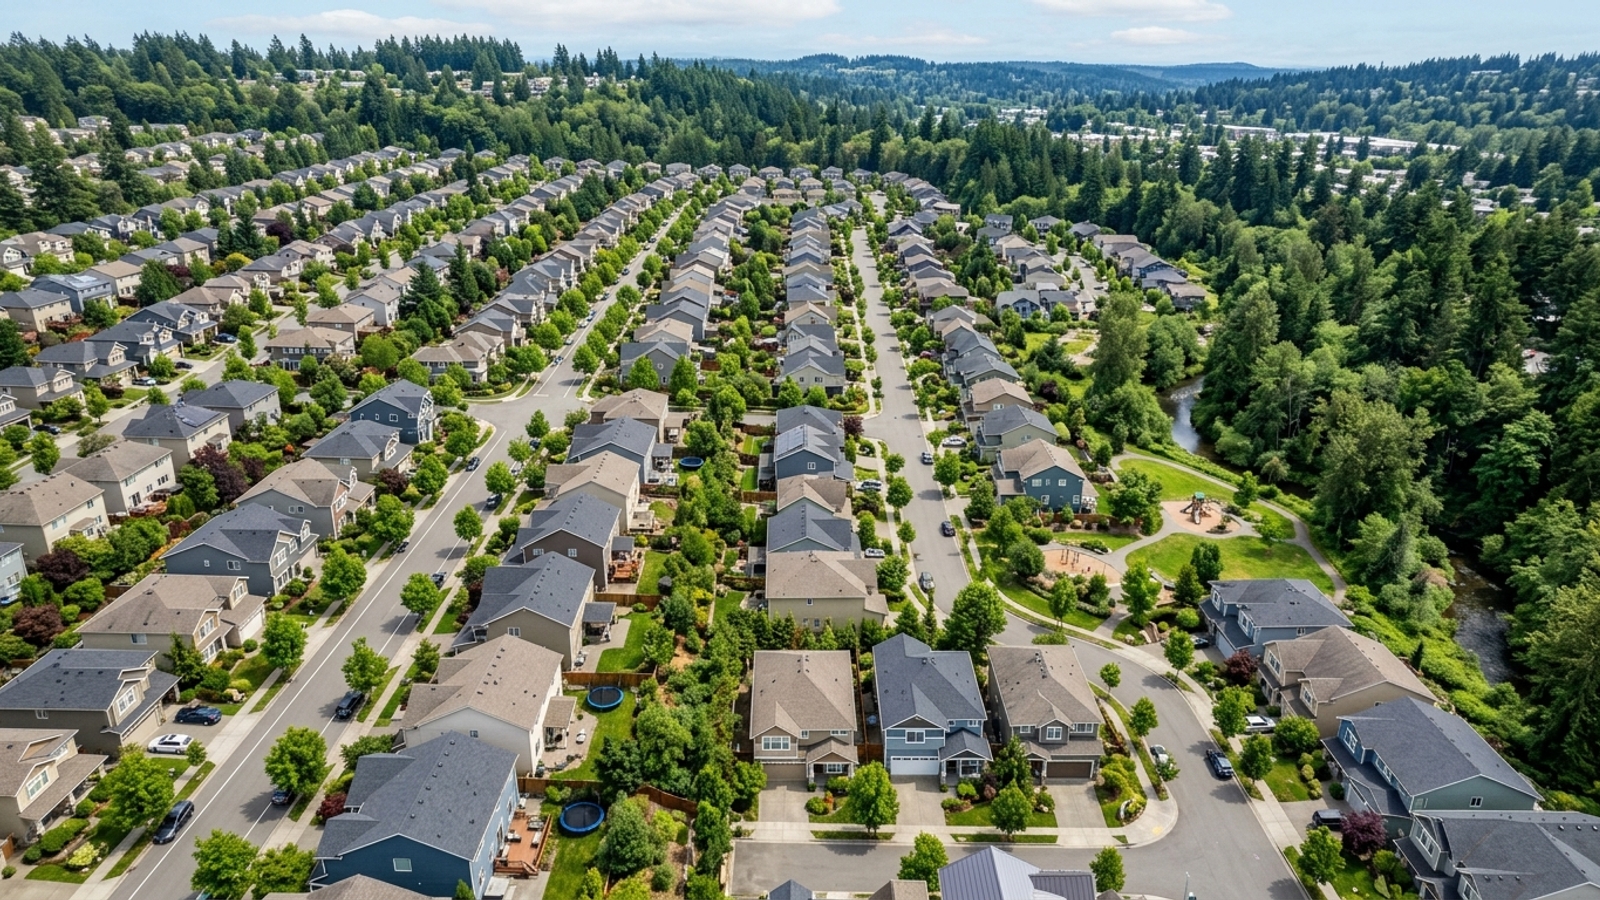
The median sale price for a home in Bothell, WA is currently around $1,033,800. At that price point, your interest rate shapes your monthly housing costs just as much as the purchase price itself - sometimes more, especially for first-time home buyers in Bothell, WA.
Whether you're looking on the King County side or the Snohomish County side, understanding how financing works gives you a real edge. Buyers who can compare loan options clearly, and sellers who understand how borrowing costs affect demand, tend to do better here.
How to Find Current Mortgage Rates in Bothell
Mortgage rates move every single business day - sometimes multiple times a day. Lenders reprice based on activity in the bond market, specifically the yield on the 10-year Treasury note. A rate you read online Tuesday morning might already be stale by Tuesday afternoon.
The only way to know your actual borrowing cost is to get a direct quote.
Where to Get an Accurate Rate Quote
Request a Loan Estimate from a lender. That's the standardized document that spells out the exact interest rate, monthly payment, and closing costs tied to your specific financial profile - not some hypothetical borrower with a perfect score and a massive down payment.
National finance sites love advertising teaser rates that assume the best-case scenario on everything. A Loan Estimate uses your actual credit history and your actual down payment. That's the number that matters.
Why Rates Fluctuate Daily
Inflation reports, employment data, and Federal Reserve policy meetings all influence how investors behave in the bond market, and that behavior drives daily rate movement. When economic data suggests inflation is cooling, bond yields typically fall and mortgage rates follow. Strong economic reports tend to push yields - and rates - back up.
What Rate Changes Mean for Your Buying Power
Bothell straddles two counties with slightly different property tax rates, ranging from roughly 0.8% to 1.1% depending on whether you buy in King or Snohomish County. Combine that with a million-dollar purchase price and the interest rate becomes the largest variable in your monthly budget - by a significant margin.
Buyers tend to fixate on the sticker price of the home. The borrowing cost is what determines the monthly check you write.
Illustrative Payment Comparisons
Take Bothell's recent median sale price of approximately $1,033,000. Put 20% down and you're financing roughly $826,400 on a 30-year fixed loan. At a 6% rate, your principal and interest payment comes to about $4,950 per month. At 7%, that same loan on that same house runs around $5,490 per month - a difference of over $500 every single month.
Same house. Different rate. Very different budget.
The Trade-Off Between Price and Rate
When rates are higher, purchasing power drops and buyers often have to look at lower-priced homes just to keep monthly payments manageable. When rates fall, buyers can borrow more for the same monthly payment - which tends to bring more buyers into the market and push prices up on available inventory.
It's a constant balancing act, and the rate is always one side of the scale.
Fixed vs. Adjustable-Rate Mortgages and Loan Types
The loan type you choose determines how your interest rate behaves over time. Lenders price different products based on the risk they carry and the length of the repayment term, so understanding the structural differences helps you align your financing with your actual plans for the property - and makes sure you're comparing apples to apples when you're shopping rates.
30-Year vs. 15-Year Fixed Options
A 30-year fixed-rate mortgage spreads payments over three decades. Lower monthly payment, but you pay more in total interest over the life of the loan, and the rate stays locked the entire time.
A 15-year fixed typically comes with a lower rate because the lender gets their money back faster. Monthly payments are higher, but the long-term interest savings are substantial.
Adjustable-Rate Mortgages (ARMs)
An ARM offers an initial fixed rate for a set period - often five or seven years - before adjusting annually based on market conditions. The introductory rate is usually lower than what you'd get on a 30-year fixed.
If you're planning to sell or refinance before that fixed period ends, an ARM can make sense. If you stay past the introductory window and market rates have risen, your payment goes up with them.
Conventional, FHA, VA, and USDA Differences
Conventional loans aren't backed by the government, and lenders reserve their best rates for conventional borrowers with strong credit. FHA loans, backed by the Federal Housing Administration, often carry slightly lower base rates but come with mandatory mortgage insurance premiums.
VA loans are available to eligible military service members and veterans - competitive rates, no down payment required, no private mortgage insurance. USDA loans serve rural areas, though most neighborhoods within Bothell city limits don't meet the rural geographic requirements for that program.
How to Get the Best Mortgage Rate as a Buyer
Lenders price risk. Your financial profile determines the rate tier you land in, regardless of what the broader market is doing. The good news is you can move that profile in your favor before you ever fill out an application.
Credit Score and Down Payments
Your credit score is the single biggest lever. Borrowers with scores above 740 generally secure the most favorable terms. Lower scores trigger pricing adjustments that push your rate up.
Down payment size matters too. Putting down 20% or more removes the private mortgage insurance requirement and often earns you a better rate - the lender has more equity protecting their position, so they charge you less for the privilege of borrowing.
Points, Buy-Downs, and Rate Locks
You can pay discount points at closing to permanently lower your rate. One point costs 1% of the total loan amount and typically reduces the rate by roughly 0.25%. It's worth doing the math if you're planning to stay in the home long-term.
Once you've found a rate you're comfortable with, lock it. A rate lock guarantees your rate for a specific window - usually 30 to 60 days - so a market move while your purchase is pending doesn't change your payment at the closing table.
Choosing a Local Mortgage Lender in Bothell
The lender you choose affects more than your monthly payment. In a market where homes go pending in roughly 26 days, a slow or unresponsive lender can cost you a house. Local lenders know the Bothell market - including the property tax differences between King and Snohomish counties - and they tend to have existing relationships with local appraisers, which keeps closing timelines from going sideways.
Comparing Banks, Credit Unions, and Brokers
Large national banks offer familiar names and online convenience, but they often move slowly and apply rigid underwriting rules. Credit unions sometimes offer lower rates or reduced fees, though you'll need to meet their membership requirements before you can apply.
Mortgage brokers don't lend their own money - they shop your profile across dozens of wholesale lenders to find the best terms available to you. Direct local lenders underwrite and fund their own loans in-house, which gives them the most control over the process and the closing timeline.
How Rate Trends Affect Bothell Home Sellers
Bothell currently has about 4.2 months of housing supply, with 192 homes in available inventory. When rates rise, buyer demand tends to cool, inventory builds, and homes sit longer.
That's the market you're pricing into. If rates are elevated when you list, buyers are already stretched by higher monthly payments - and pricing your home accurately is what keeps your listing from becoming stale inventory.
Pricing and Timing Your Listing
Buyers shop based on what they can afford each month, not on list price alone. If rates jump right before you go on market, the pool of buyers who can afford your home at your asking price gets smaller - it's that direct.
Sellers who offer concessions like paying for a buyer's temporary rate buy-down often generate more interest than those who simply cut the price. A buy-down addresses the monthly payment problem directly while keeping the final sale price intact. That distinction matters more than it might seem.
Mortgage Rate FAQs
What are mortgage rates today in Bothell, WA?
Because rates change daily based on bond market activity, the only way to get today's accurate rate is to request a direct quote. A standardized Loan Estimate from a lender will show the exact rate you qualify for based on your credit profile.
Should I wait for rates to drop before buying a home in Bothell?
Waiting carries its own risk. If borrowing costs fall, more buyers typically enter the market, which can drive up the current median sale price of roughly $1,033,000. Focus on whether the monthly payment fits your current budget rather than trying to time the market.
How much does a 1% difference in mortgage rate cost me on a Bothell home purchase?
On a loan of $826,400 - typical for a Bothell home with 20% down - moving from a 6% rate to a 7% rate adds over $500 to the monthly principal and interest payment.
How do I get the best mortgage rate as a buyer in Bothell?
Optimize your credit score and save for a larger down payment. Borrowers with scores above 740 and a 20% down payment generally receive the most favorable pricing from lenders.
How do I choose a mortgage lender in Bothell, WA?
Interview local direct lenders, credit unions, and mortgage brokers - compare loan products and pay attention to how they communicate. Local professionals understand the property tax differences between the King and Snohomish county portions of Bothell and can often close faster than national call centers.
Will today's mortgage rates make it harder to sell my house in Bothell?
Higher rates reduce buyer purchasing power, which can push days on market up and inventory higher. With Bothell currently at about 4.2 months of supply, accurate pricing and concessions like rate buy-downs can make a real difference in attracting budget-conscious buyers.
Getting Local Guidance in Bothell
The financial side of a real estate transaction has a lot of moving parts, and the specifics of the Bothell market - two counties, different tax rates, fast-moving inventory - matter when you're making these decisions. Before you commit to a loan product or put your home on the market, it's worth sitting down with someone who works this market every day.
A local agent can give you context on recent sale prices, what's happening with inventory, and how current financing conditions are shaping buyer behavior right now. They can also connect you with local lenders who have a track record of closing on time in Bothell - which, at 26 days to pending, you'll want.
Mindy Newton
| Greater Sound Team Real Estate | Real Broker LLC
or another way